The real
cost, disclosed.
Federal law makes lenders show the true cost of credit in one standard box before you sign. We build every page around that same box — for every loan type, before you ever apply.
The cost of your credit as a yearly rate. 391%
The dollar amount the credit will cost you. $45.00
The amount of credit provided to you. $300.00
What you'll have paid after all payments. $345.00
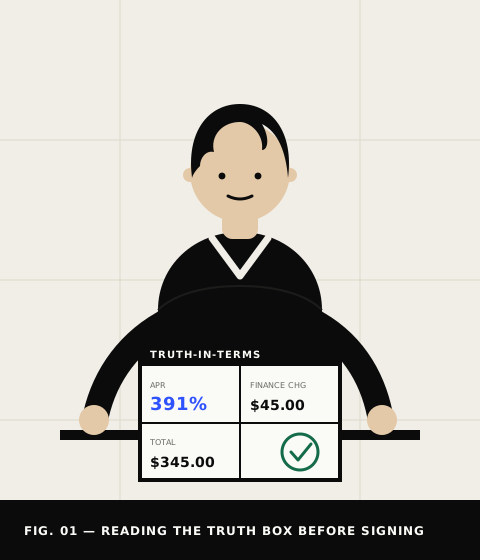
Someone about to sign something they haven't fully read.
That's most of us, most of the time. Loan paperwork is written to be skimmed, not read — dense clauses, a flat fee up front, the real cost buried three paragraphs down. We built the Truth Box and the Ledger so the number that actually matters is the first thing you see, not the last.
Why We Built It This WayThe Ledger
Five loan types, entered side by side the way an auditor would — same columns, same standard, no marketing language.
| Loan Type | Typical APR | Term | Amount | Audit Mark | Best Fit |
|---|---|---|---|---|---|
| EXHIBIT 01Payday Loan | 300–400%+ | 1–4 weeks | $100–$500 | Hazard | One-time gap, repaid next check |
| EXHIBIT 02Installment Loan | 25–200% | 3–24 months | $500–$5,000 | Caution | Planned expense, sustainable plan |
| EXHIBIT 03Title Loan | 200–300% | 30 days | Up to vehicle value | Hazard | Rarely lowest-cost; last resort |
| EXHIBIT 04Cash Advance App | Varies (tip-based) | Days, tied to payday | $20–$250 | Clear | Small, short timing gaps |
| EXHIBIT 05Line of Credit | 20–36% | Revolving | Varies | Caution | Recurring, unpredictable costs |
Redaction Reveal
Real loan offers often bury the costly parts in vague language. Click each black bar below to declassify it and see the plain-English version underneath.
This agreement includes a due at your next pay date. Your loan will unless you contact us before the due date. To be approved, you agree to provide . Your rate and terms are . This offer does not require .
Audit Notes
A few habits that matter more than which lender you pick.
Ask for the APR out loud
If you only hear a flat dollar fee, ask directly: "What's the APR on this?" Lenders are required to disclose it.
Ask what happens if you're late
Get the answer in writing — a fee, a rollover, repossession. A vague answer is a red flag on its own.
Compare the total payoff, not the payment
The full amount you'll have paid by the time the loan is done — that's the number that matters.